|
Marie Antoinette, Queen of France (1774 to 1792), was said to have declared, “Let them eat cake.”
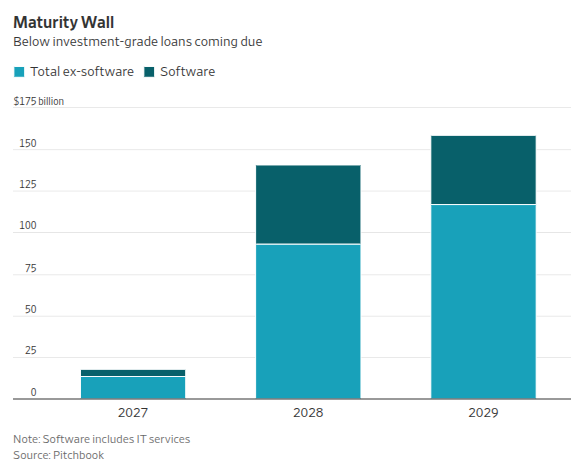
More than two centuries later, that sentiment has found a new audience in global credit markets. Capital remains plentiful for the strongest borrowers, but increasingly scarce for the weakest. Not everyone will have access to capital, and for those with deteriorating creditworthiness, the cost of borrowing is becoming intolerable.
The credit markets are "A Tale of Two Cities" (also about the French Revolution), the haves and the have-nots, as the bottom half of the K-shaped economy feels the pinch from tighter financial conditions, a rather peculiar development since GDP growth is robust. This tale is being played out across the AI complex, the delta between BBs and CCCs, and even in sovereign credit, as French OATs are feeling the heat.
When the largest borrowers absorb trillions, the marginal borrower pays up or simply fails to raise capital, the lifeblood of existence.
The buildout of data centers in the U.S. is projected to cost nearly $10T over the next 5 years, which is 3.6% of GDP per annum. However, I will take the under, as many projects will not have the capital, power, or regulatory approval to proceed. The four largest hyperscalers are expected to spend over $1T annually (we will get more information this week when they report earnings and discuss their CapEx plans), but with strong profits, multi-trillion-dollar market caps, and AA ratings, these companies can access credit as they build their AI moats. While on-B/S financing may be slightly wide to the IG index, off-B/S debt trades at an extra +100 bps spread.
The neoclouds are relegated to the HY market, where credit availability has become problematic. Today, the largest, most successful neocloud's debt trades at 15%, and its 5-year CDS trades at ~1,100 bps, which is unsustainable. Gartner expects 80% of neoclouds to cease independent operation by 2030, as a shake-up is coming. The hyperscalers with strong balance sheets are in a position to pick up the pieces.
France's 5.4% fiscal deficit, debt-to-GDP ratio of 120%, and 10-year OAT yield above 5% saw its spread to Bunds reach 178 bps last week. France pays more than Italy, putting its credit rating at risk. In the U.S., 6% deficits are not favorable either. However, access to capital is the key, and despite a $2 trillion funding gap for the current fiscal year, the market is open and willing. This crowds out other borrowers by raising the "risk-free" rate. When sovereigns pay more, everyone pays more.
IG spreads and BBs are below long-run averages, while CCC spreads have blown out to ~1,300 bps, the widest on record during a time of prosperity (i.e., "let them eat cake").
Takeaway 1: It's a lender’s market.
Takeaway 2: 2027 should be great for Direct Lending and Opportunistic Credit; the best vintages occur when capital is scarce, spreads are wide, and lenders are selective.
|