Creditor Corner
|
|
|
|
Your weekly curated content from the Creditor Rights Coalition
|
|
Over 3,700 member subscribers and growing!
We bring you exclusive content from leading data and research providers
Sign Up Here
|
|
In This Week’s Creditor Corner
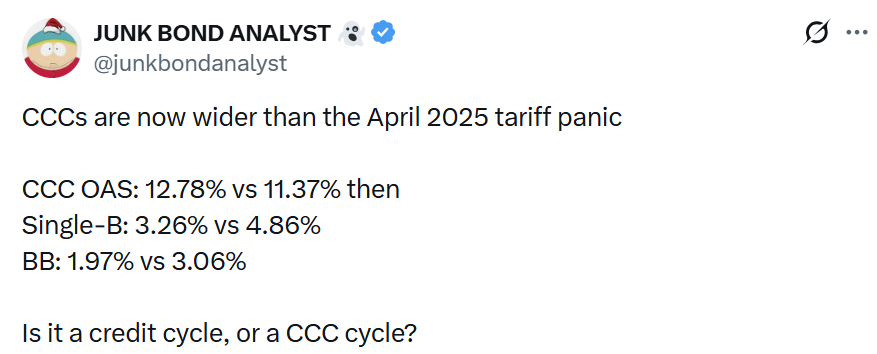
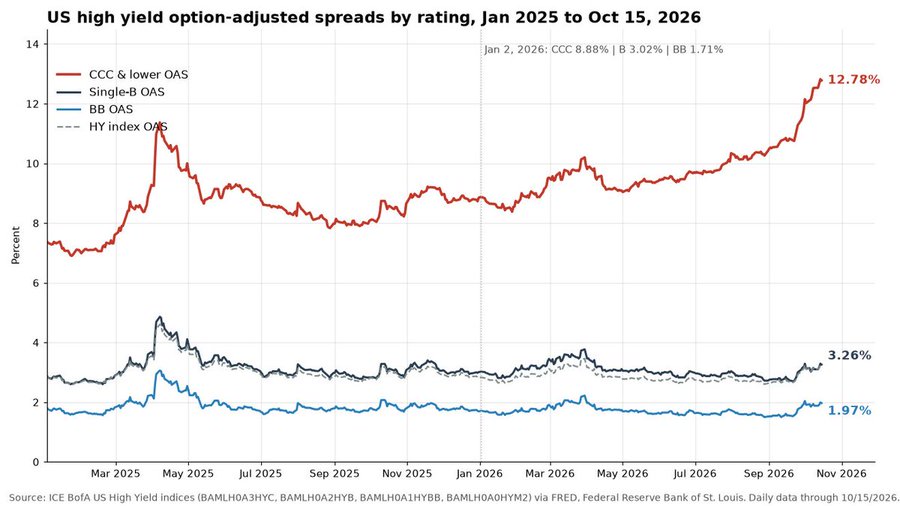
HY and AI volatility and market divergence, Getty picture-perfect prepack, Six Flags on a roller coaster, Altice creditors challenge Drahi’s playbook, JetBlue encounters turbulence and much, much more…
Featured Content
Jeffrey Finger on the Restructuring Playbook
&
Bruce Richards on The Markets
|
|
Scroll through to read all our content
|
|
|
|
Exclusive Content
|
|
AI Infrastructure, Built on Borrowed Time?
|
 |
 |
|
Click above to access content
|
|
Our take:
Apparently, even AI can’t outsmart the cost of capital. CoreWeave’s unsecured bonds have fallen to distressed levels, with some trading around 80 cents, while weakness spreads to Zenith Arc and Galaxy Helios. But the bigger concern isn’t necessarily slowing AI demand. It’s whether heavily leveraged infrastructure providers can justify enormous capital expenditures when financing costs rise and assumptions around GPU values, construction timelines and future revenues become less certain. The AI revolution may be real, but that doesn’t guarantee everyone financing it will survive.
|
|
|
|
|
|
Featured Content
|
|
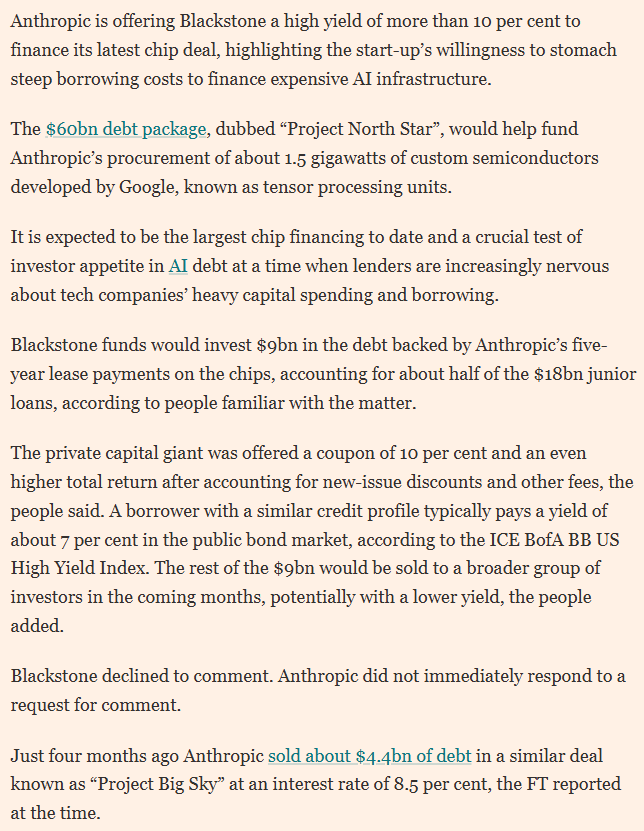
Even Anthropic is joining HY
|
 |
 |
|
|
|
|
|
|
Featured Content
|
|
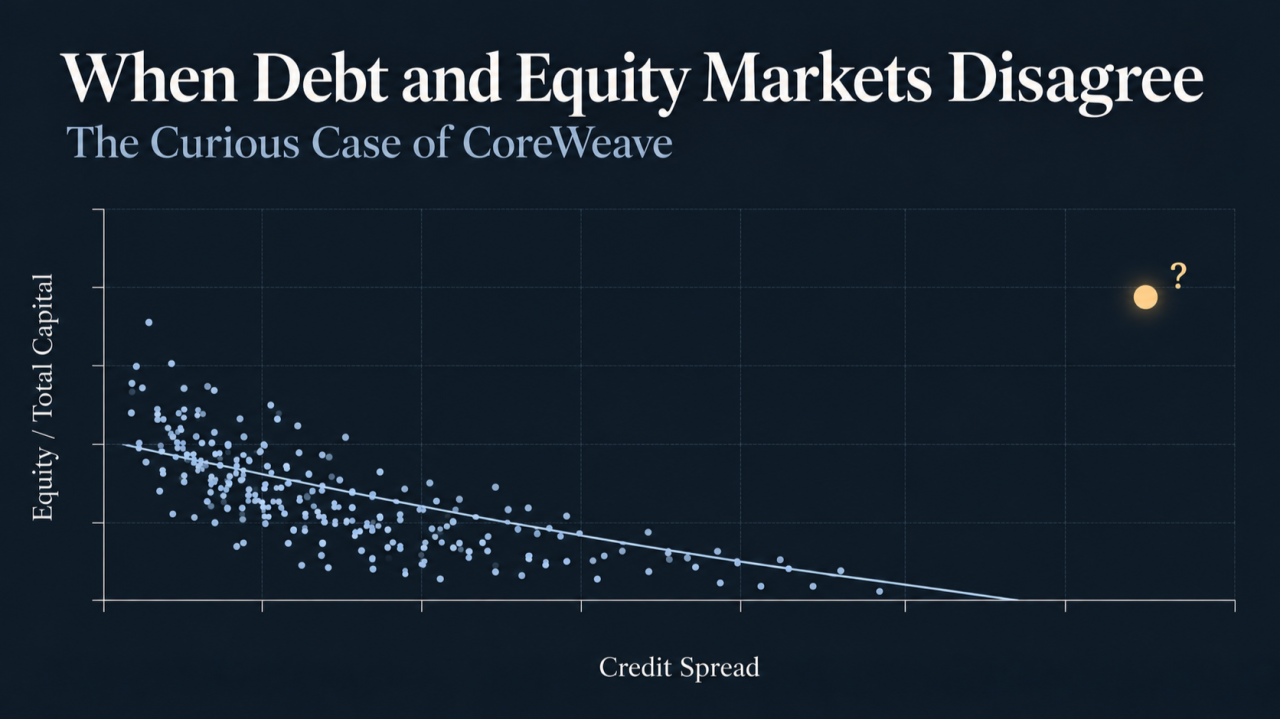
When Credit and Equity Don’t See Eye to AI
|
 |
|
Click above to access content
|
|
Our take:
Same company, two very different market verdicts. Despite unsecured notes yielding nearly 15%, CoreWeave still commands an equity valuation of roughly $37bn. Either CoreWeave is a true unicorn, or one side of the market has some serious repricing to do.
|
|
|
|
|
|
Exclusive Content
|
|
Picture-Perfect Prepack
|
 |
 |
|
Click above to access content
|
|
Our take:
In an era of over-levered LMEs with a road to nowhere, it is refreshing to see a traditional deleveraging with shareholders forgiving debt and contributing new money in exchange for capturing discount, interest rate savings and a deleveraged capital structure. All the more shocking that this came from the new home of Nemececk. Could we be seeing a kinder-gentler Nemececk?
In an era of overleveraged LMEs on a road to nowhere, it is refreshing to see traditional deleveraging: shareholders forgiving debt and contributing fresh capital to capture a discount, lower interest costs and strengthen the balance sheet. Even more surprising is that it comes from Nemecek’s new home. Could we be seeing a kinder, gentler Nemecek?
|
|
|
|
|
|
Exclusive Content
|
|
Restructuring: The Sequel
|
|
 |
|
Click above to access content
|
|
Our take:
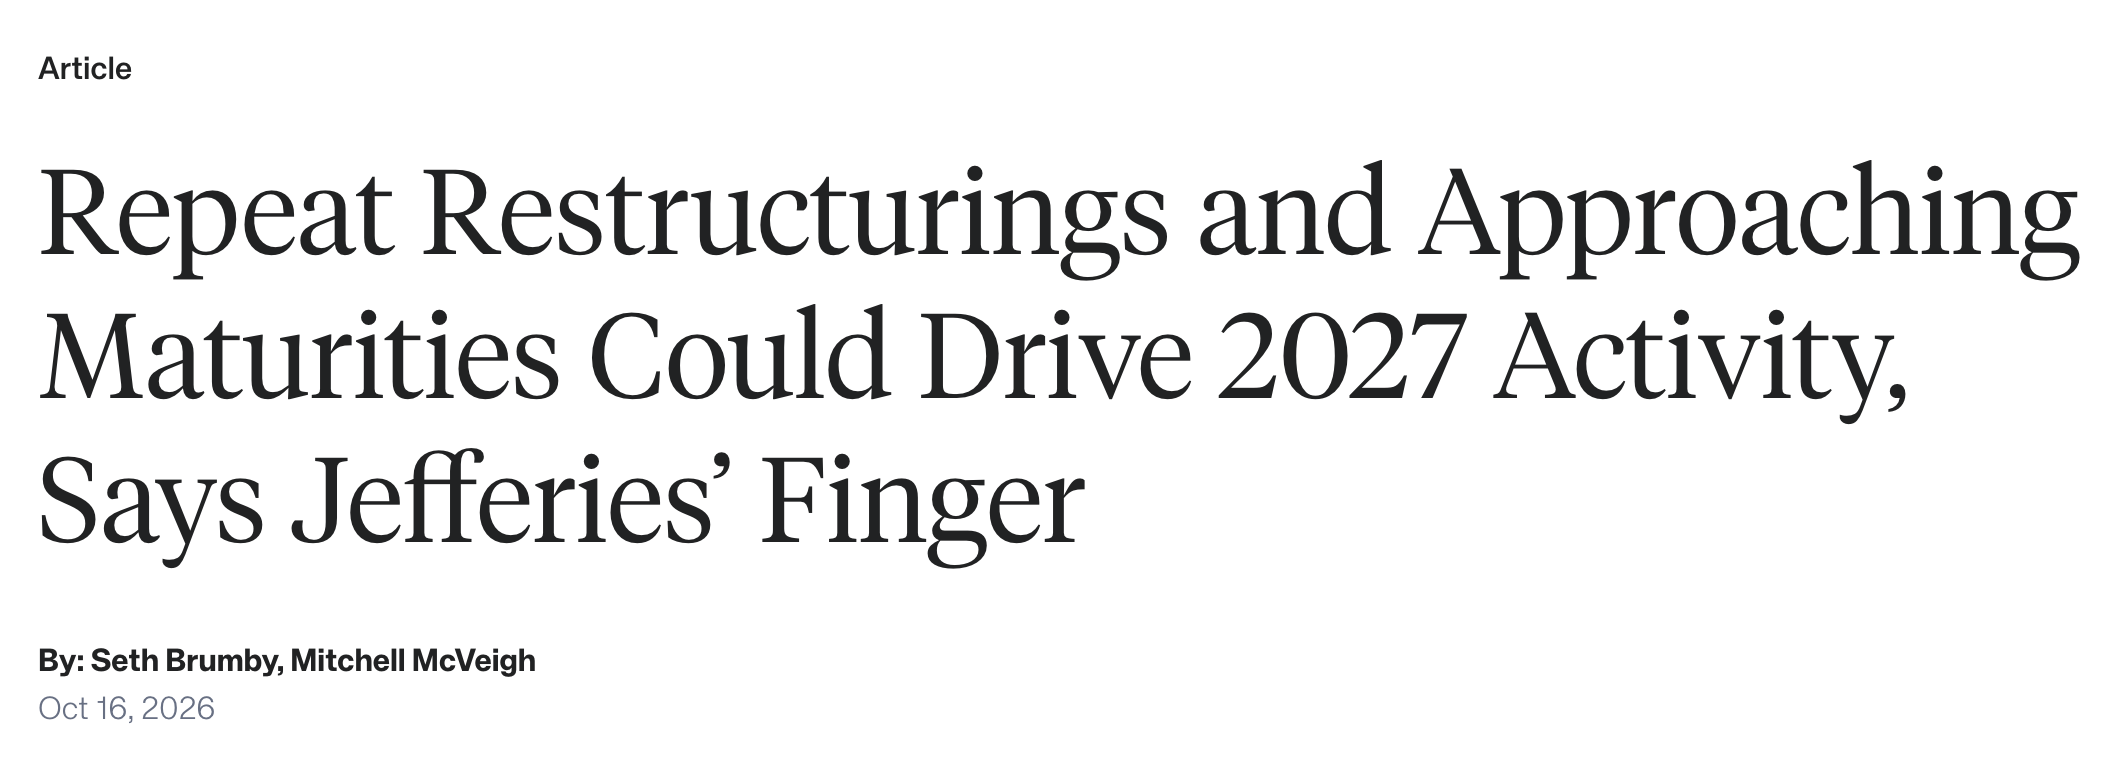
So it seems that one restructuring isn’t always enough. With 2028–29 maturities approaching, Jefferies expects some companies that completed LMEs over the past two years to find themselves back at the negotiating table in 2027.
The problem? Extending maturities without fixing underlying liquidity or leverage issues may only postpone the inevitable. For creditors, the next round could mean tougher negotiations, greater pressure for sponsor contributions and a reminder that buying time isn’t the same as solving the problem. We think Jefferies is onto something with its approach here…
|
|
|
|
|
|
Exclusive Content
|
|
A Steep Drop for Six Flags
|
 |
|
 |
|
Click above to access content
|
|
|
|
|
|
In the News
|
|
Hain’s Recipe for Distress
|
 |
 |
|
Click above to access content
|
|
|
|
|
|
Exclusive Content
|
|
A Rough Landing Ahead?
|
 |
|
Click above to access content
One-time registration required
|
|
|
|
|
|
Exclusive Content
|
|
The Altice Way or the Highway
|
|
 |
|
Click above to access content
|
|
Our take:
The so-called “Altice Way” is facing its day in court. Creditors holding more than $11bn in debt allege that Patrick Drahi-controlled entities transferred billions in assets beyond their reach, challenging five transactions across 27 claims. With Altice’s 2027 maturities approaching, the outcome could have significant implications for recoveries and lenders’ negotiating leverage.
|
|
|
|
|
|
Featured Content
|
 |
|
The Software Hangover Is Not Going Away
Software is a major component of the approaching maturity wall that I discussed yesterday in my daily post.
On one end of the extreme, large publicly listed software companies with little net debt (average is ~0.5x), those with strong moats and substantial cash generation are well positioned as the Rule of 40 defines success for this sector. These businesses with proprietary data, cybersecurity franchises, or software embedded in mission-critical hardware systems and high switching costs have actively invested through the AI transition to become AI-first software enterprises, positioned well for the future.
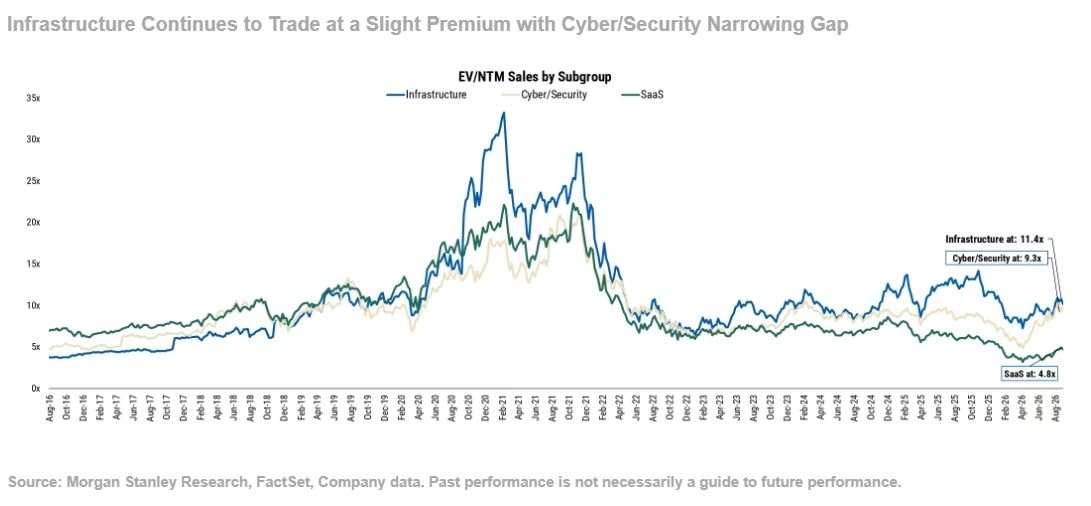
There is a big difference between a public software company that has an infra or cyber moat vs. SAAS as you see below in this table. Private companies, smaller enterprises are obviously much less valuable.
At the other end of the spectrum there are the 1,000+ smaller, sponsor-backed SaaS companies, levered 6x, 8x or 10x debt-to-EBITDA, that are far more susceptible. Their products are often vertical, with a customer base that is more concentrated while their technology is significantly easier to replicate as the cost of software development falls.
As token prices fall, the cost of building, maintaining and replicating software declines sharply. A small team of developers using Cursor, Claude Code or Codex, may be able to recreate comparable enterprise functionality in days rather than years.
Consider a borrower at 10x debt-to-EBITDA. The sponsor may claim 6.5x after add-backs for “one-time” costs that recur annually. A recurring expense is not one-time.
Important questions to consider are:
Will strong historical retention translate into durable ARR over the next five years?
Can margins be defended as enterprise code can increasingly be produced at token prices legacy vendors cannot match?
Will agentic AI reduce seat counts, compress ARR and weaken revenue durability?
If coding costs approach zero, what happens to competitive moats and terminal value?
BDCs and Direct Lending funds hold several hundred billion dollars of software exposure. The risk is now much better understood.
With eyes wide open, few lenders are currently willing to extend new credit on prior terms.
Where new loans are available, they often provide only two to three years of runway, priced at +100 to +200 basis points of additional spread, cash-flow and leverage covenants required, and 5% to 10% annual amortization. New software credit likely support only around 4x leverage, if financing can be obtained.
Existing lenders are willing to waive covenants, permit PIK, or extend maturities in an effort to avoid default, requested a cash sweep if the sponsor is negotiable in an effort to avoid a technical default.
Amend and pretend delays loss recognition. Kick the can down the road has become too familiar a strategy in private credit.
And yes, I am sticking with my call, this maturity wall will lead to a default wall.
|
 |
|
Click above to access content
To follow Bruce’s thoughts on the markets, investing and more, follow
@bruce_markets
|
|
|
|
|
Featured Content
|
|
Really?????
|
 |
 |
 |
|
Click above to access content
|
|
Our take:
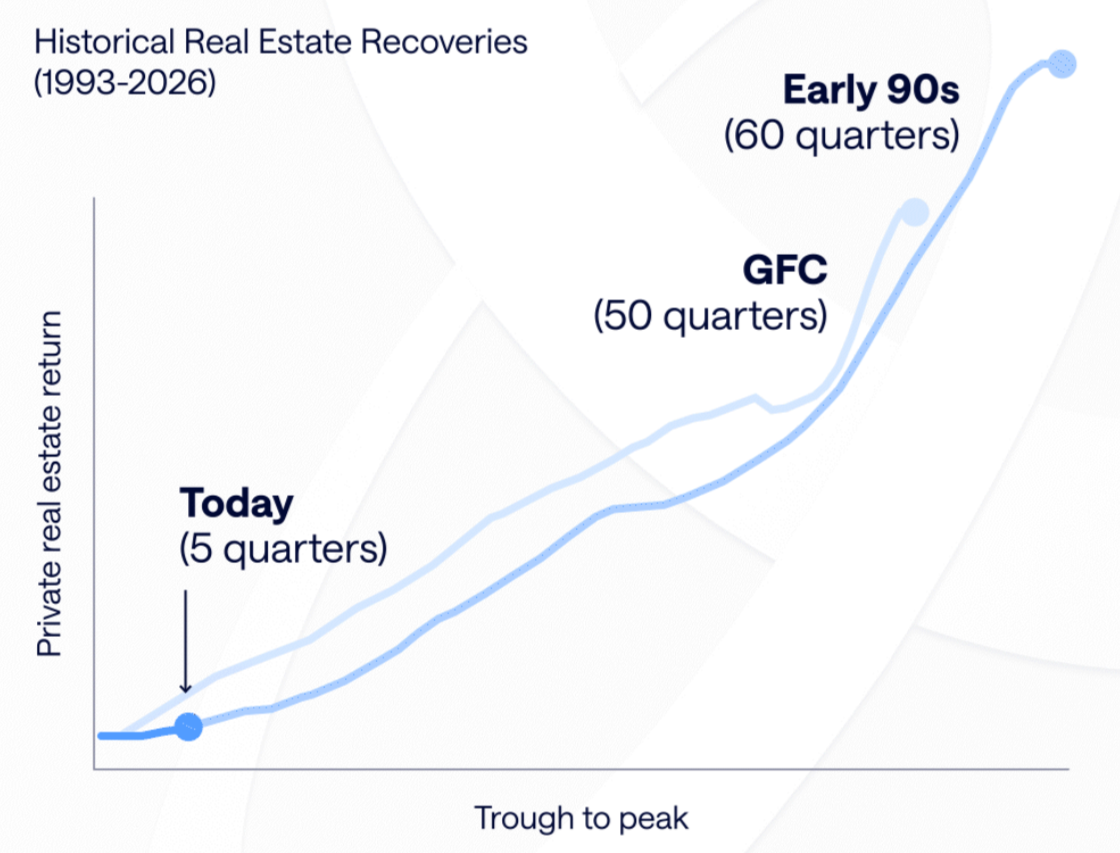
Ares believes real estate bottomed in Q3 2024 and is now enjoying a multiyear recovery. Not everyone is buying it. Commenters point to unresolved distressed assets, years of kicking the can down the road and questions around fund liquidity as reasons to question the optimism. The bigger question for creditors: is the market genuinely recovering, or have lenders simply gotten better at postponing the reckoning? The bottom may be behind us, but the jury is still out.
|
|
|
|
|
|
|
 |
|
Hot Topics in Bankruptcy: 4Q26
|
|
October 21, 2026
|
| Learn More |
|
|
|
|
 |
|
9fin: Data and AI in debt capital markets
|
|
October 29, 2026
|
| Learn More |
|
|
|
|
 |
|
INSOL International: Singapore’s Latest Insolvency Reforms
|
|
October 30, 2026
|
| Learn More |
|
|
|
|
 |
|
ABI: International European Insolvency Symposium
|
|
November 2, 2026
|
| Learn More |
|
|
|
|
|
|
 |
|
TMA NY 21st Annual Holiday Cocktail Reception | Honoring the Bankruptcy Judges
|
|
November 5, 2026
|
| Learn More |
|
|
|
|
 |
|
ABI: International North American Insolvency Symposium
|
|
November 10, 2026
|
| Learn More |
|
|
|
|
 |
 |
|
AIRA: Restructuring & Plan of Reorganization Conference
|
|
November 16, 2026
|
| Learn More |
|
|
|
|
 |
|
Debtwire Restructuring Forum Miami 2026
|
|
December 7-8, 2026
|
| Learn More |
|
|
|
|
The Data Download
|
|
Bringing Transparency to the Bankruptcy Process
|
 |
 |
 |
 |
 |
 |
|
Click Above to Access The Data Download
|
|
Our Take:
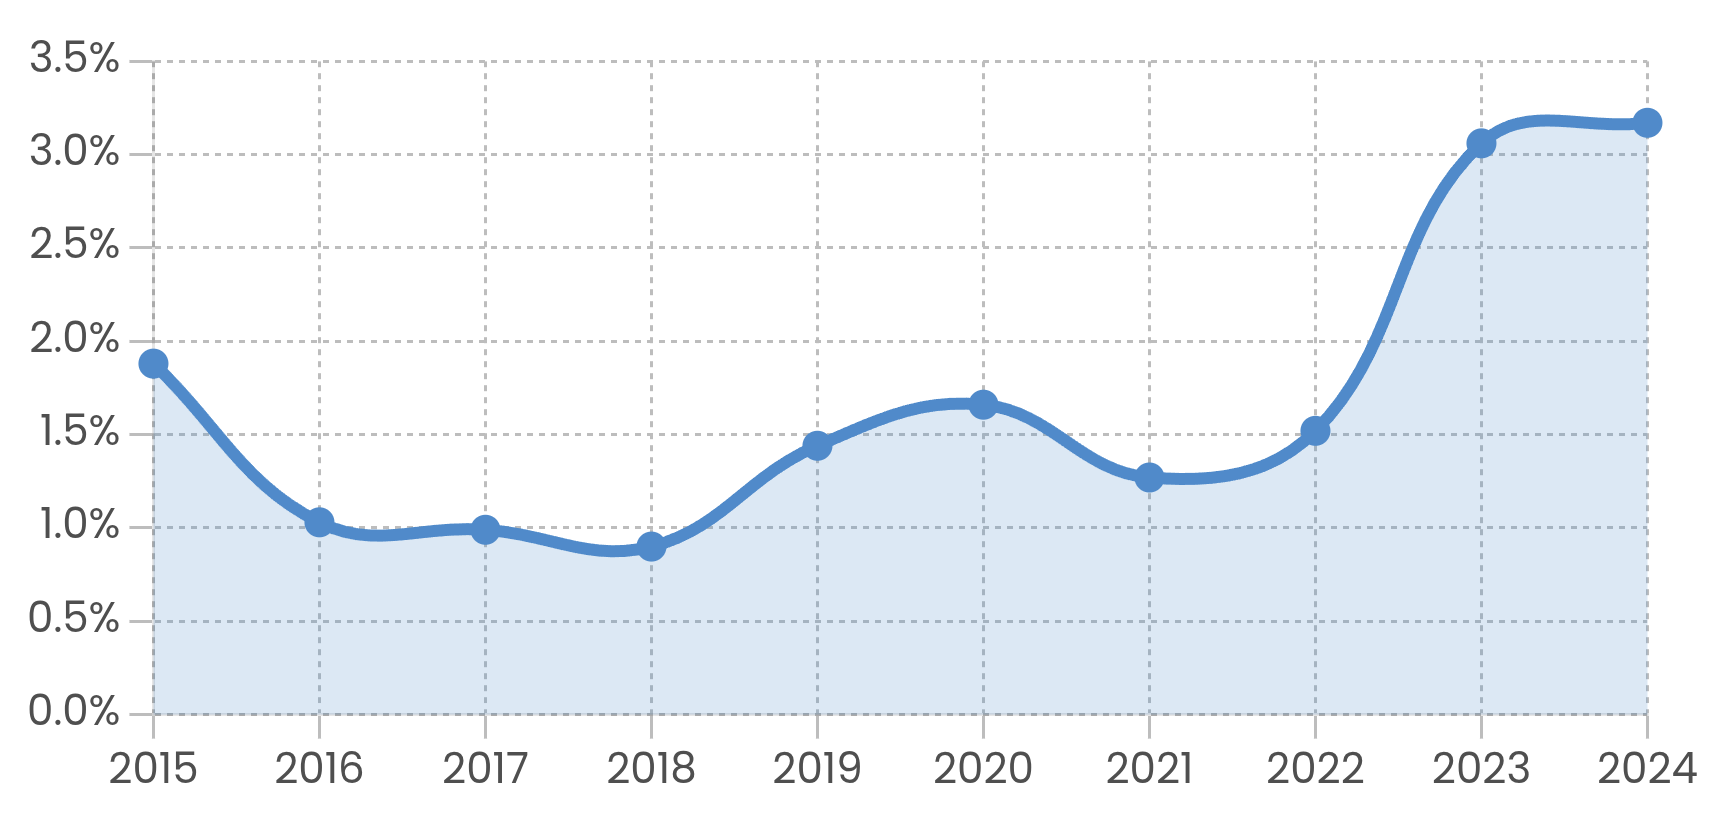
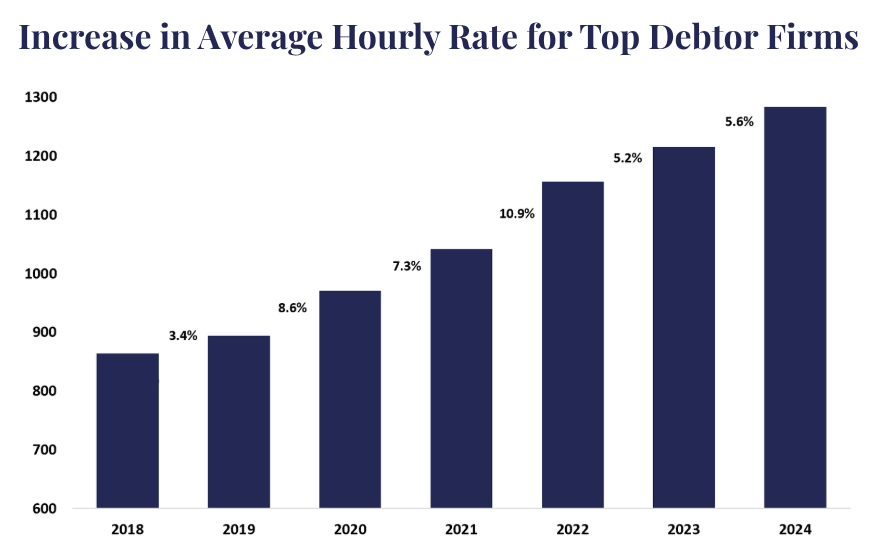
The Daily Cost of BK Legal fees Are Increasing.
Are we shocked? No.
We took a deep dive to see what is driving up the daily cost of restructurings and the culprit: Increasing Legal Hourly Rates. We analyzed final fee apps for top debtor law firms from 2018 to 2024 and found average hourly legal fees have increased by over 65% since 2018. Maybe a little bit of sunlight is the right disinfectant to help remedy the problem…
|
|
|
|
|
|
|